
Newsletter [Aug 30 - Sept 5]
Good Morning
A note from our CEO, Richard Roman Jr
Freight conditions remain challenging as we enter September.
While broad market indices have begun showing some stabilization, the rates we are seeing in the market continue to move higher on a number of services. Equipment availability, carrier allocations, port congestion, and routing-specific capacity remain significant factors, particularly as we approach the fall shipping season and China’s upcoming holiday period.
This is an important distinction: the overall market does not need to increase uniformly for an importer to experience higher freight costs. The right equipment, sailing, and routing can still be considerably tighter than the headline market suggests.
At the same time, trade uncertainty remains elevated. The U.S.–Canada trade dispute continues, Section 301 tariffs are now firmly part of the customs landscape, and the Administration continues focusing on trade imbalances and foreign manufacturing practices.
For importers, September will be about managing both transportation and landed cost carefully.
The Roundup
What moved the world this week
Customs & Trade Policy Update
U.S.–Canada Trade Dispute Continues
The U.S.–Canada trade dispute remains one of the largest trade-policy developments affecting North American supply chains.
Canada recently announced retaliatory tariffs covering approximately $20 billion of annual U.S. imports, with duties of 15%, 25%, and 50% scheduled to take effect September 8.
The dispute is already beginning to influence sourcing and investment decisions across North America.
Automotive supply chains remain particularly exposed because vehicles and components frequently cross the U.S.–Canadian border multiple times during production.
For importers and manufacturers operating across North America, USMCA qualification, country of origin, and sourcing decisions are becoming increasingly important.
Section 301 Remains a Major Focus
The Administration continues relying heavily on Section 301 as part of its trade strategy.
The new Section 301 tariffs covering 60 economies for forced-labor-related trade practices remain in effect, while additional investigations involving countries including Vietnam and Germany remain active.
For importers, this reinforces an important change in the tariff environment.
Duty exposure increasingly needs to be evaluated based on:
Country of origin
HTS classification
Applicable Section 301 actions
Section 232 exposure
AD/CVD applicability
Available exclusions or special treatment
Tariff planning is becoming increasingly product- and country-specific.
Pressure Builds Around Global Trade Imbalances
Trade policy discussions this week also focused heavily on manufacturing overcapacity and global trade imbalances.
At the G20 meetings, the United States received support from most participating finance ministers for efforts addressing non-market policies and trade distortions, with much of the discussion focused on China’s manufacturing and export model.
This is important for importers because USTR already has an active Section 301 investigation into structural excess capacity and production in manufacturing sectors.
While no new tariffs resulted from this week’s discussions, it remains an area worth monitoring closely.
Additional trade actions targeting specific countries or industries remain possible as the Administration continues reshaping U.S. tariff policy.
Hormuz Disruption Continues Reshaping Cargo Flows
Middle East disruption continues affecting global shipping patterns.
Cargo that historically moved through Gulf ports is increasingly being rerouted through alternative gateways. Jordan’s Port of Aqaba, for example, has experienced significant growth in transit cargo destined for Iraq as shippers seek alternatives to routes affected by Strait of Hormuz disruption.
These changes matter beyond the Middle East.
Longer routings consume vessel capacity, containers, trucking resources, and equipment that would otherwise be available elsewhere in the global network.
This remains another factor contributing to equipment positioning challenges worldwide.
Supply Chain & Logistics News
Freight Rates Remain Elevated as Equipment Issues Continue
Freight pricing remains elevated across many of the trade lanes we are quoting.
Drewry’s latest World Container Index showed some stabilization, with its global index decreasing 1% to $4,473 per 40-foot container. Shanghai–New York declined 2% to $9,333, while Shanghai–Los Angeles remained approximately unchanged at $6,818.
However, those benchmarks don’t tell the entire story.
Importers continue facing:
Equipment shortages at specific origins
Carrier allocation restrictions
Port congestion
Vessel schedule disruptions
Blank sailings
Routing-specific capacity shortages
Shanghai congestion also increased significantly recently, with average vessel waiting times rising to approximately 96 hours from 35 hours the previous week.
Our View
The market is becoming increasingly fragmented.
A broad freight index may show stability while an individual importer sees its actual rate increase significantly because the required equipment or preferred sailing is unavailable.
This is why we continue recommending that clients provide forecasts early and allow us to evaluate multiple carriers and routings rather than relying on a single service.
Blank Sailings Continue Into September
Carriers are not abandoning capacity management.
Drewry currently projects 45 blank sailings across the major East–West trades between August 31 and October 4, representing approximately 6% of scheduled sailings.
At the same time, fewer immediate Trans-Pacific cancellations suggest some capacity is returning to the market.
That creates an interesting balance heading into September: carriers want to maintain elevated pricing, but additional capacity could eventually create more competition if demand begins to moderate.
We will continue watching whether current freight levels can hold as September progresses.
JR Global LCL Spotlight
Promotional LCL Rate: Thailand → New York
Not every shipment needs a full container.
For importers with smaller volumes from Thailand, JR Global is currently offering a promotional LCL consolidation rate:
Laem Chabang, Thailand → New York
$185 / CBM – Ocean Freight
Our LCL consolidation service provides importers with an alternative to waiting until they have enough cargo to fill a container or paying for unused FCL capacity.
This can be particularly valuable for:
Smaller purchase orders
Regular replenishment shipments
Sample and initial production orders
Importers looking to reduce inventory commitments
Cargo that cannot wait for the next FCL order
JR Global coordinates the shipment from origin consolidation through arrival in New York, with customs clearance and final delivery services also available.
Promotional space is limited. Contact our team for schedules and eligibility.
The Forecast
Trends, goals, and what’s on the radar at JR Global
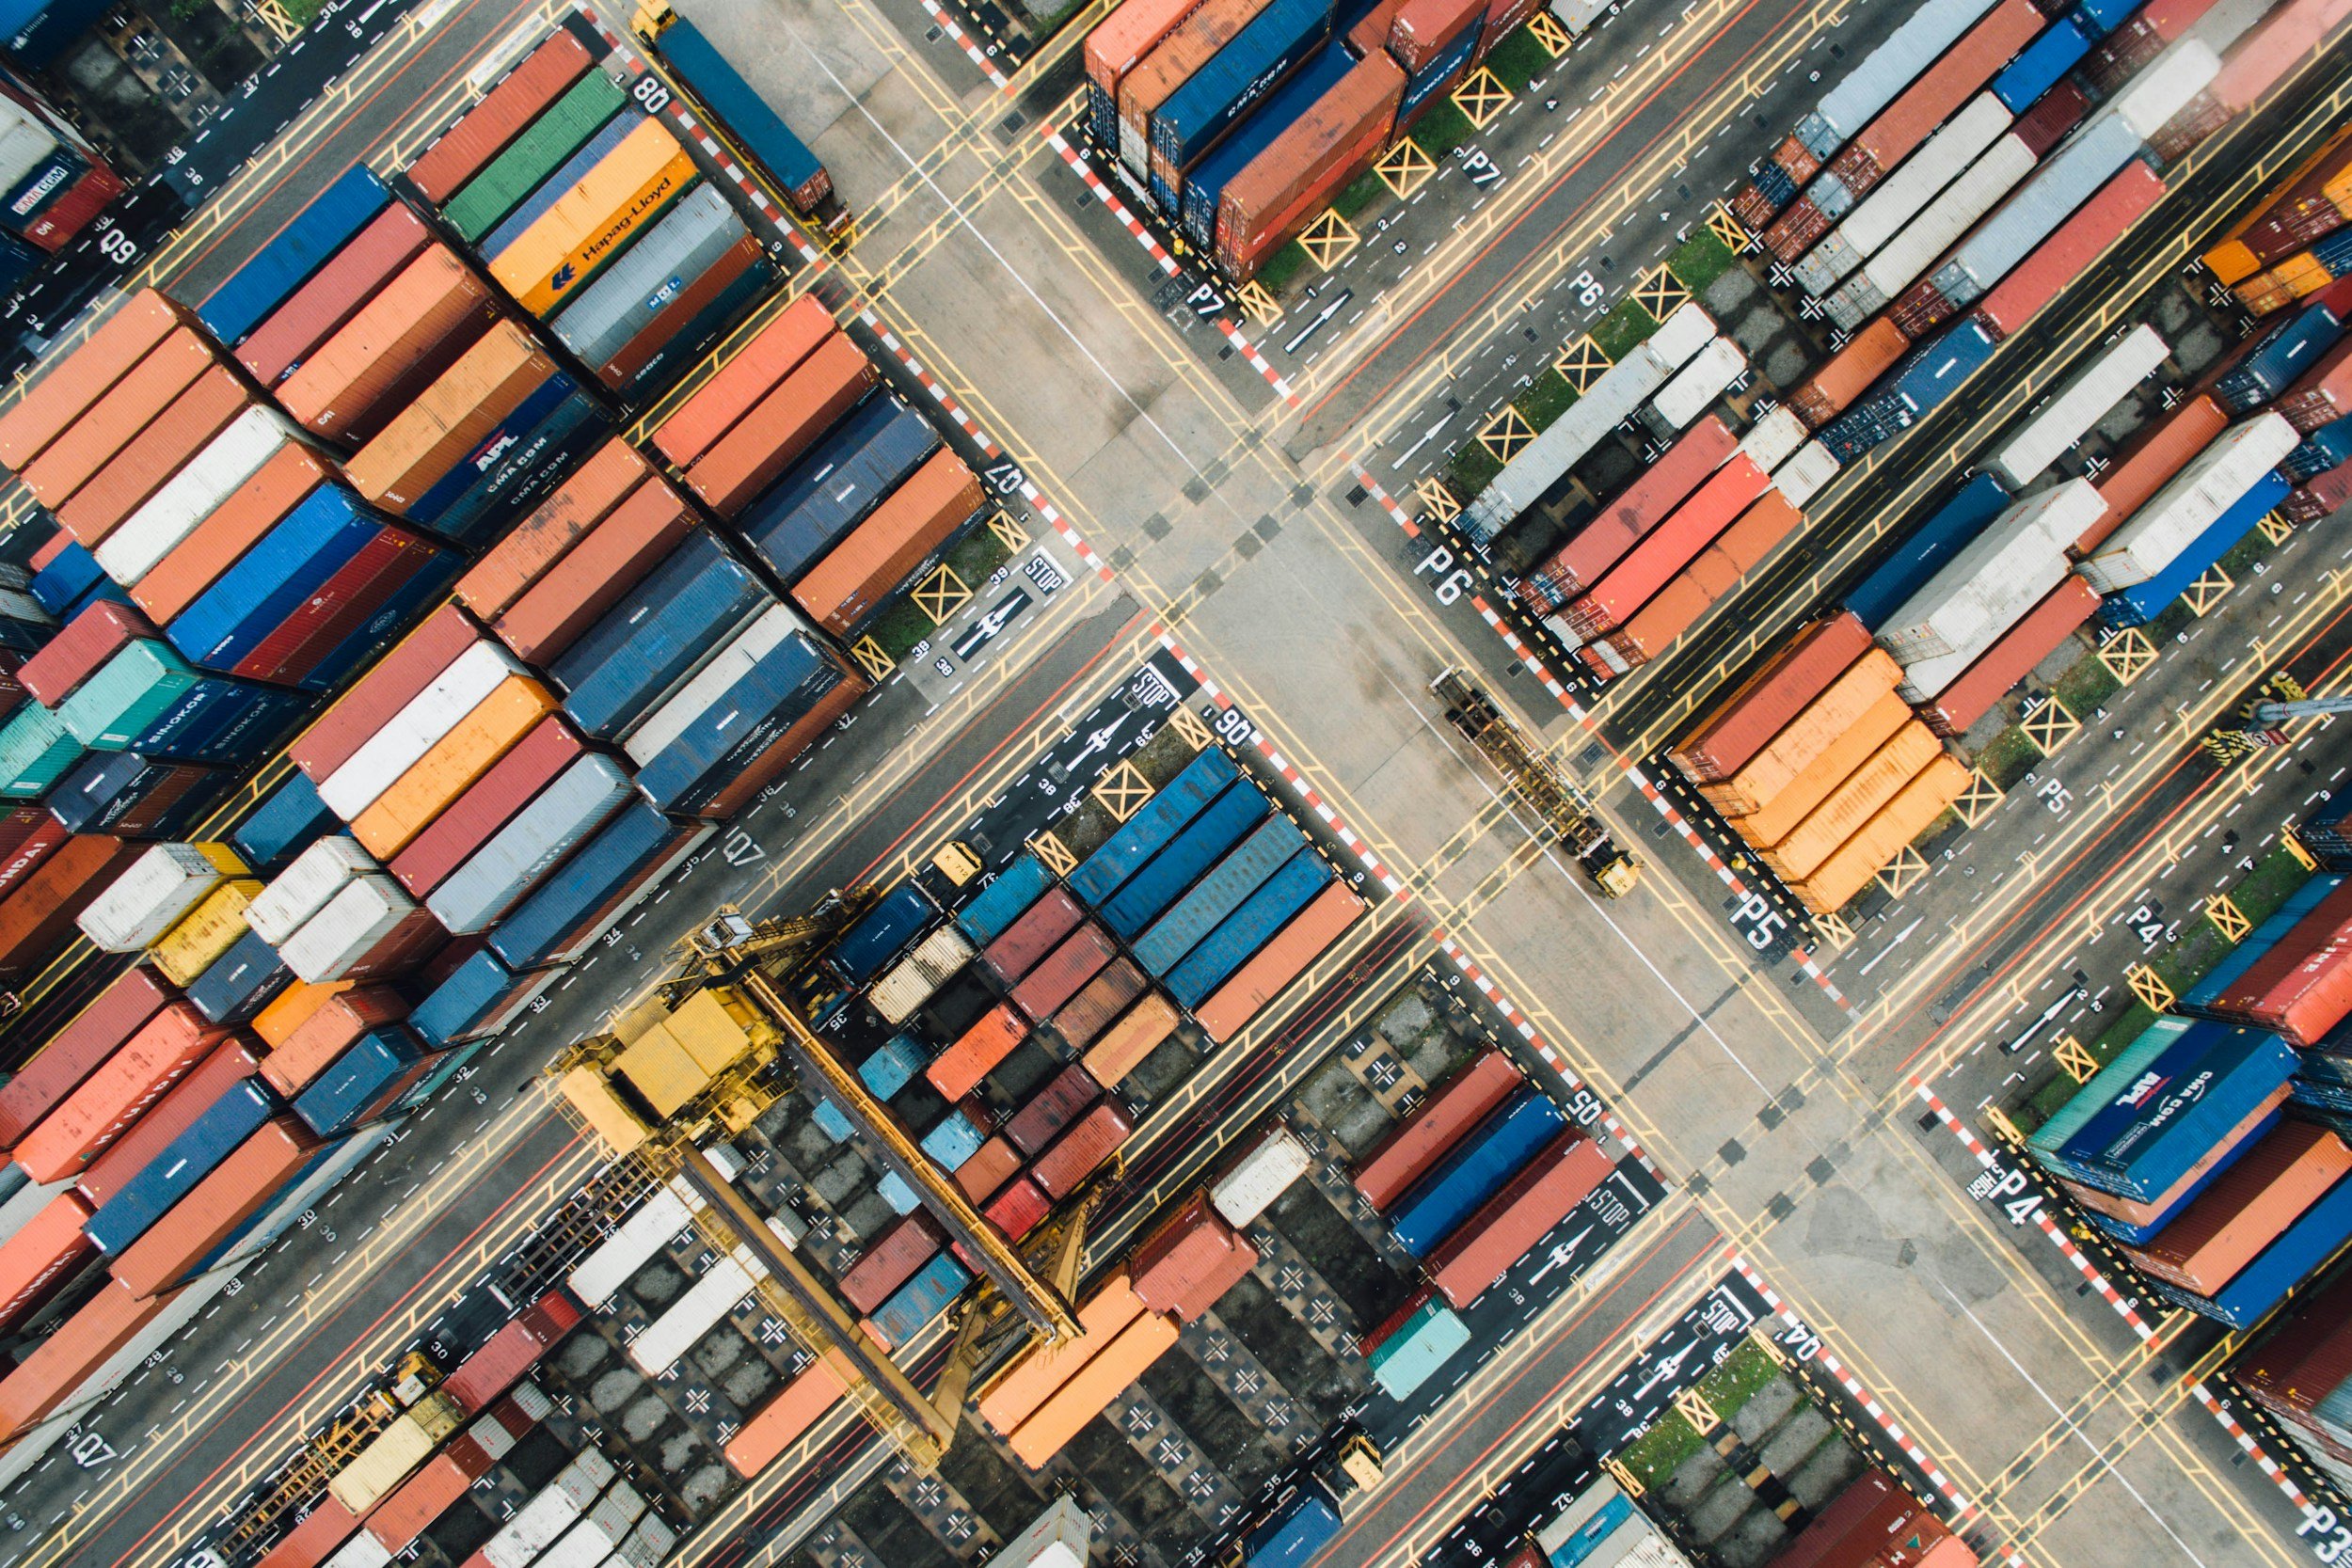
September will be an important month for freight markets.
We are closely monitoring:
Equipment availability across Asia
China port congestion
Blank sailings
Trans-Pacific booking volumes
Upcoming China holiday demand
U.S.–Canada trade developments
Additional Section 301 actions
Global trade and manufacturing investigations
Our expectation is that the market will remain uneven.
Certain trade lanes may begin seeing more competitive pricing as capacity returns, while specific origins and services experiencing equipment shortages could remain significantly elevated.
This is a market where comparing options matters.
The Shortcut
Smart tips for smart shippers
Freight rates remain elevated across many of the services we’re quoting.
Equipment availability continues creating origin-specific pricing pressure.
Shanghai port congestion recently increased significantly.
45 blank sailings are currently projected across major East–West trades through early October.
JR Global is offering promotional LCL ocean freight from Laem Chabang to New York at $185/CBM.
Canada’s retaliatory tariffs on U.S. goods are scheduled to begin September 8.
Section 301 remains a major component of U.S. tariff policy.
USTR continues active investigations involving additional countries and trade practices.
Global manufacturing overcapacity is becoming an increasingly important trade-policy issue.
The Playlist
What the JR team is listening to this week in the office
Follow Us
Stay in the loop with JR Global
Instagram: https://www.instagram.com/shipjrglobal
TikTok: https://www.tiktok.com/@shipjrglobal
Facebook: https://www.facebook.com/shipjrglobal
Join Our Team
We are hiring at JR Global